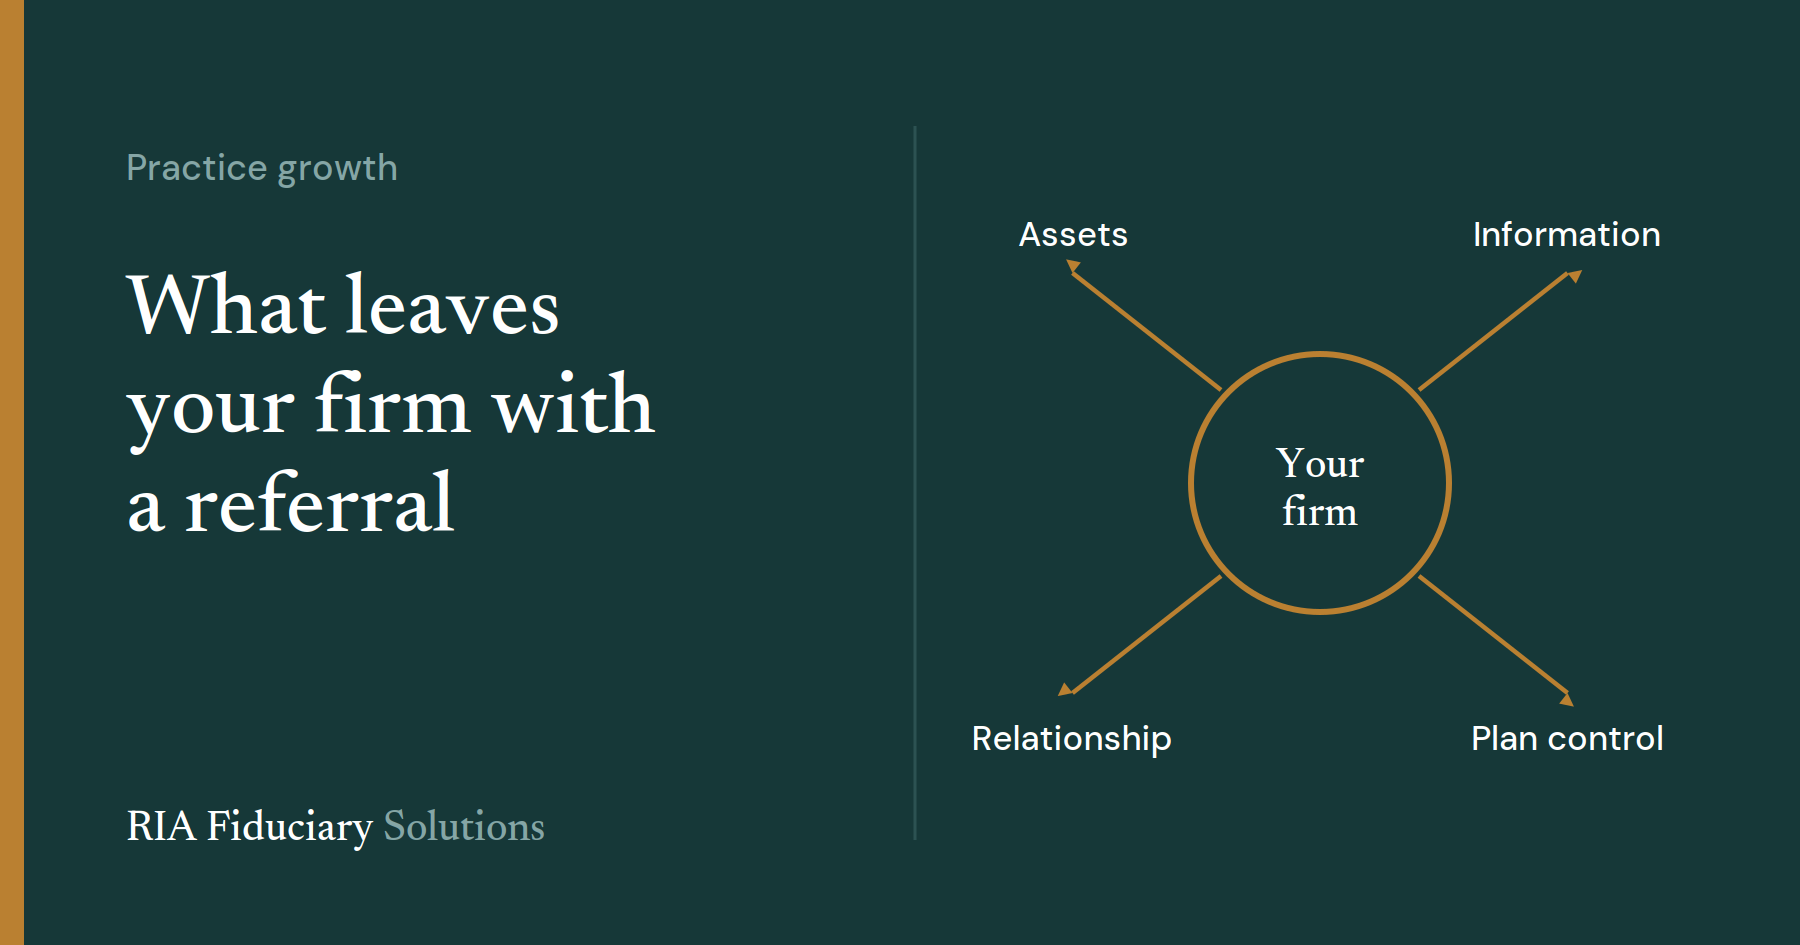
- When you refer annuity business out, assets, information, and part of the relationship often leave with it.
- Not offering annuities isn’t neutral. The client still buys one, just outside your plan.
- A four-step process keeps the decision with you: spot the need, bring in your desk, design inside the plan, and service without a handoff.
How a referral turns into a leak
It usually starts with good intentions. A client asks about guaranteed income. Your firm doesn’t handle annuities, so you pass along the name of an insurance agent you trust.
Six months later, the annuity is on a statement you don’t see, funded with money that used to sit in the account you manage. The agent has your client’s phone number, birthday, and a reason to call every year. You have a note in your CRM.
Four things left your firm in that exchange:
- The assets. Money that moves into an annuity you don’t advise on usually leaves your fee base.
- The information. With the contract off your statements, your plan now runs on partial data.
- Part of the relationship. Another professional now has a standing reason to talk with your client.
- Control of the plan. Someone who didn’t build the plan chose a product that now shapes it.
“We don’t do insurance” isn’t neutral
Many firms treat staying out of annuities as the conservative choice. But the client’s need doesn’t go away. The annuity still gets bought. The only question is whether it’s designed inside your plan or outside it.
The 4-step path that keeps it in-house
Step 1: Spot the need early
Build annuity questions into moments you already have: approaching retirement, a 401(k) rollover, an inherited annuity, a large market decline, or an old contract showing up on a client’s balance sheet. The earlier you raise it, the less likely the client goes looking elsewhere.
Step 2: Bring the case to your desk
Instead of handing over a name, send the plan context, the client’s goals, and any existing contracts to your outsourced desk. You stay in the middle of the conversation.
Step 3: Design inside the plan
Review options and trade-offs with the desk, then present the recommendation to your client yourself, as part of the plan you already built together.
Step 4: Execute and service without a handoff
Applications, issue, and servicing run through the desk, with contract data flowing back to your systems. Service requests come through you, so the relationship stays where it started.
Find your own leaks
Three quick checks show how much this matters in your practice:
- How many clients did you refer out for insurance or annuities in the last twelve months?
- How many held-away annuities show up on your clients’ balance sheets?
- How often did a client ask about guaranteed income when you didn’t have a ready answer?
If those numbers aren’t zero, see how the main annuity models compare or start with a review of the contracts already in your book.
Bring us the next client who asks about income or an old annuity. You stay planner of record; we handle design, paperwork, and servicing behind you.
Start an analysisQuestions advisors ask
Will your desk contact my clients directly?
RIA Fiduciary Solutions works only with advisors. You stay planner of record and stay in the middle of the client relationship.
What if my client already bought an annuity elsewhere?
It can still be reviewed. Depending on the contract, the right answer may be to keep it, change how it’s used, or replace it once surrender charges no longer apply.