- State insurance law, not securities law, decides whether being paid for annuity advice requires an insurance-related license.
- Rules differ from state to state, and they can depend on where your client lives as well as where your firm is.
- Having an outsourced desk place the contract doesn’t automatically answer whether your fee is covered. Get a written opinion from counsel.
Fee-based annuities have made it far easier for RIAs to include protected income in a client plan. The product side has gotten simpler. The licensing side has not.
Insurance is regulated state by state. Your investment adviser registration covers advice about securities. Many annuities used in advisory accounts, including fixed and fixed indexed annuities, are not securities at all. Advice about them can fall outside your adviser registration and inside state insurance law. Variable annuities and registered index-linked annuities are both securities and insurance, so both sets of rules can apply.
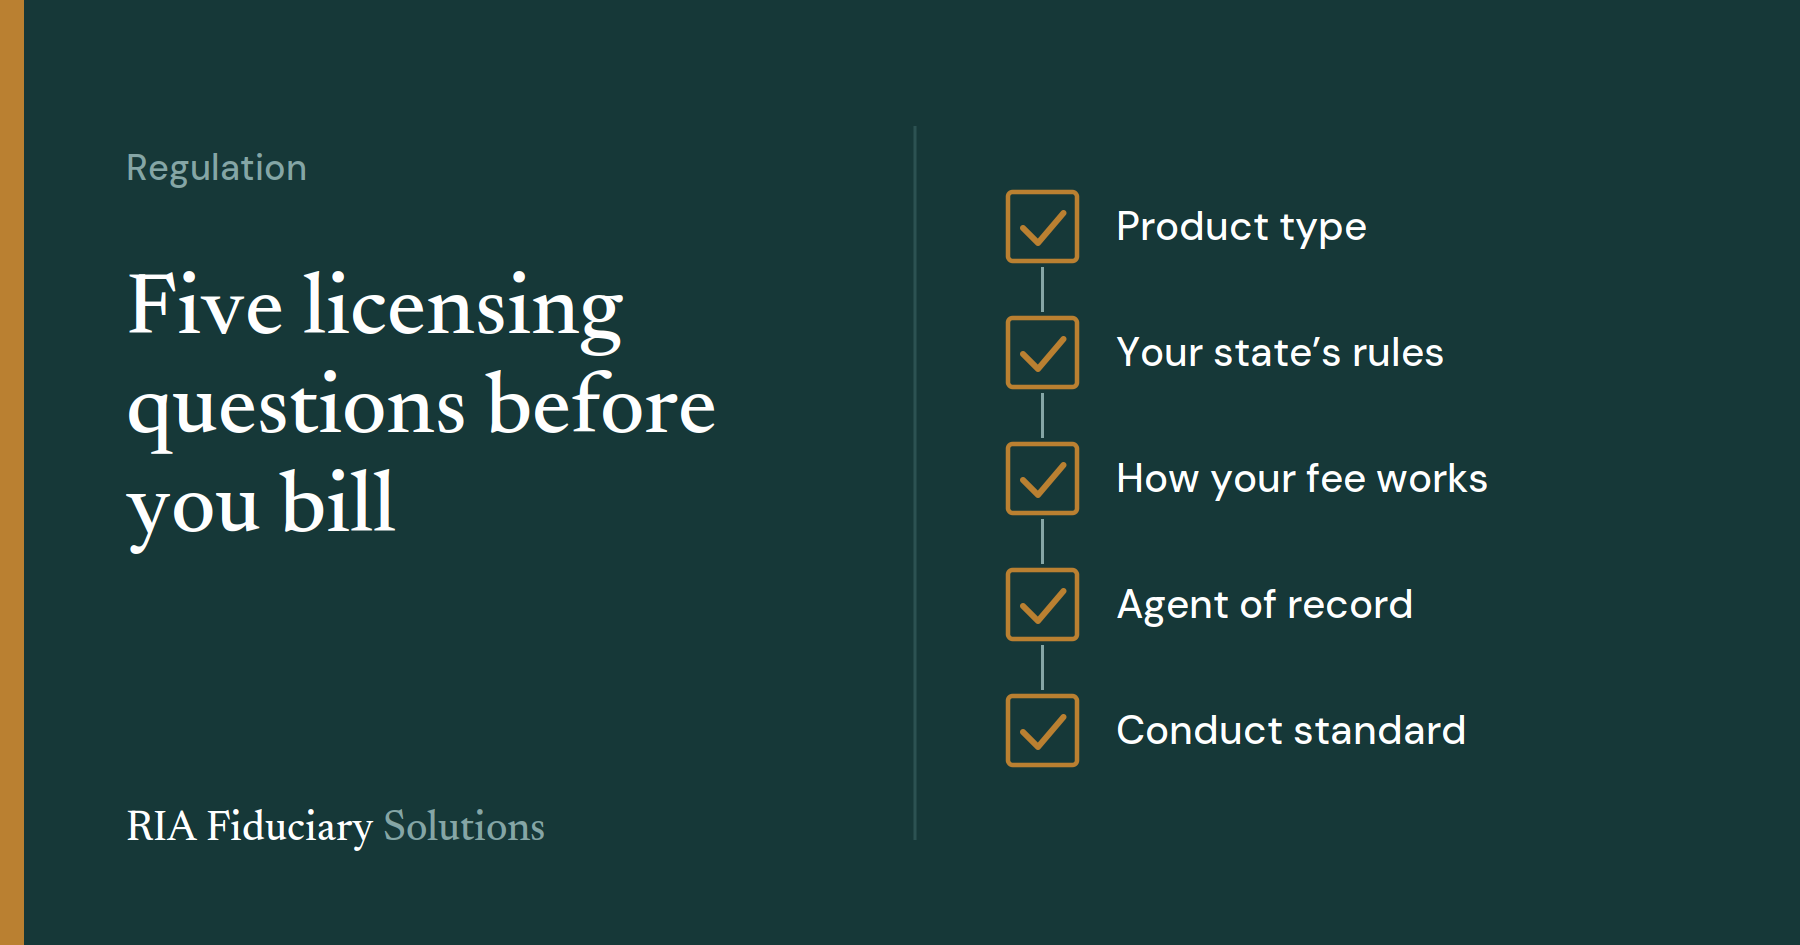
That leaves one practical question for your firm: when you earn a fee connected to an annuity, which license does your state expect you to hold? These five questions help you get a clear answer.
1. Is the product a security, insurance, or both?
Start with each product type your firm recommends or bills on. A fixed or fixed indexed annuity is an insurance product. A variable annuity or registered index-linked annuity is also a registered security. The answer determines which regulators have a say.
2. What does your state say about being paid for insurance advice?
States take different approaches. Some license insurance consultants or counselors who charge a fee for advice about insurance. Some require a producer license to receive any compensation connected with an insurance recommendation. Others have no specific rule. Check both the state where your firm operates and the states where your clients live.
3. How exactly is your fee calculated and described?
An asset-based fee that includes annuity values, a flat planning fee, and an hourly fee for a specific annuity recommendation may be treated differently. Make sure your Form ADV, client agreement, and invoices describe the fee the same way, and that the description matches how you actually work.
4. Who is agent of record, and what does your agreement with them cover?
When an outsourced desk is agent of record, its licensed people handle the sale. That covers the placement. It does not necessarily answer whether your firm’s advice about the annuity, or your fee on it, needs its own license in a given state. Read your agreement with the desk and ask counsel how the two roles fit together.
5. Which conduct standards apply to your role?
Most states have adopted a best-interest standard for annuity recommendations made by insurance producers. Your firm also owes clients a fiduciary duty as an investment adviser. Know which standard applies to each person involved in a recommendation and document that each was met.
What to do this quarter
- List every state where you have clients who own annuities, or may soon.
- List every way your firm earns a fee connected to an annuity.
- Ask counsel for a written opinion on each combination, and file it with your compliance records.
- Update your Form ADV and client agreements to match the answer.
- Put a yearly reminder on the calendar. State rules change.
How RIA Fiduciary Solutions works alongside this
As agent of record, our team holds the licenses and carrier appointments needed to place and service the contracts we handle. We can share how other firms have set up their workflows with us. We can’t give legal advice about your firm’s licensing, and we’d rather your counsel be part of the conversation from the start.
To see how the licensing question fits into the bigger decision, read how to choose an annuity model for your RIA.
Tell us how your firm handles annuities today and where your clients live. We’ll walk through how a case would work with us, so you can bring specific questions to your counsel.
Talk to our deskQuestions advisors ask
Doesn’t my investment adviser registration cover advice about annuities?
It covers advice about securities. Fixed and fixed indexed annuities are insurance products, not securities, so advice about them may fall under state insurance law instead. Confirm with counsel for your states.
If an outsourced desk places the annuity, is my firm covered?
The desk’s license covers the placement. Whether your firm needs its own insurance-related license to earn a fee tied to that annuity depends on state law and how your fee works.
Do the rules depend on where my firm is or where my client lives?
Potentially both. Check the rules in your home state and in each state where clients who own annuities reside.