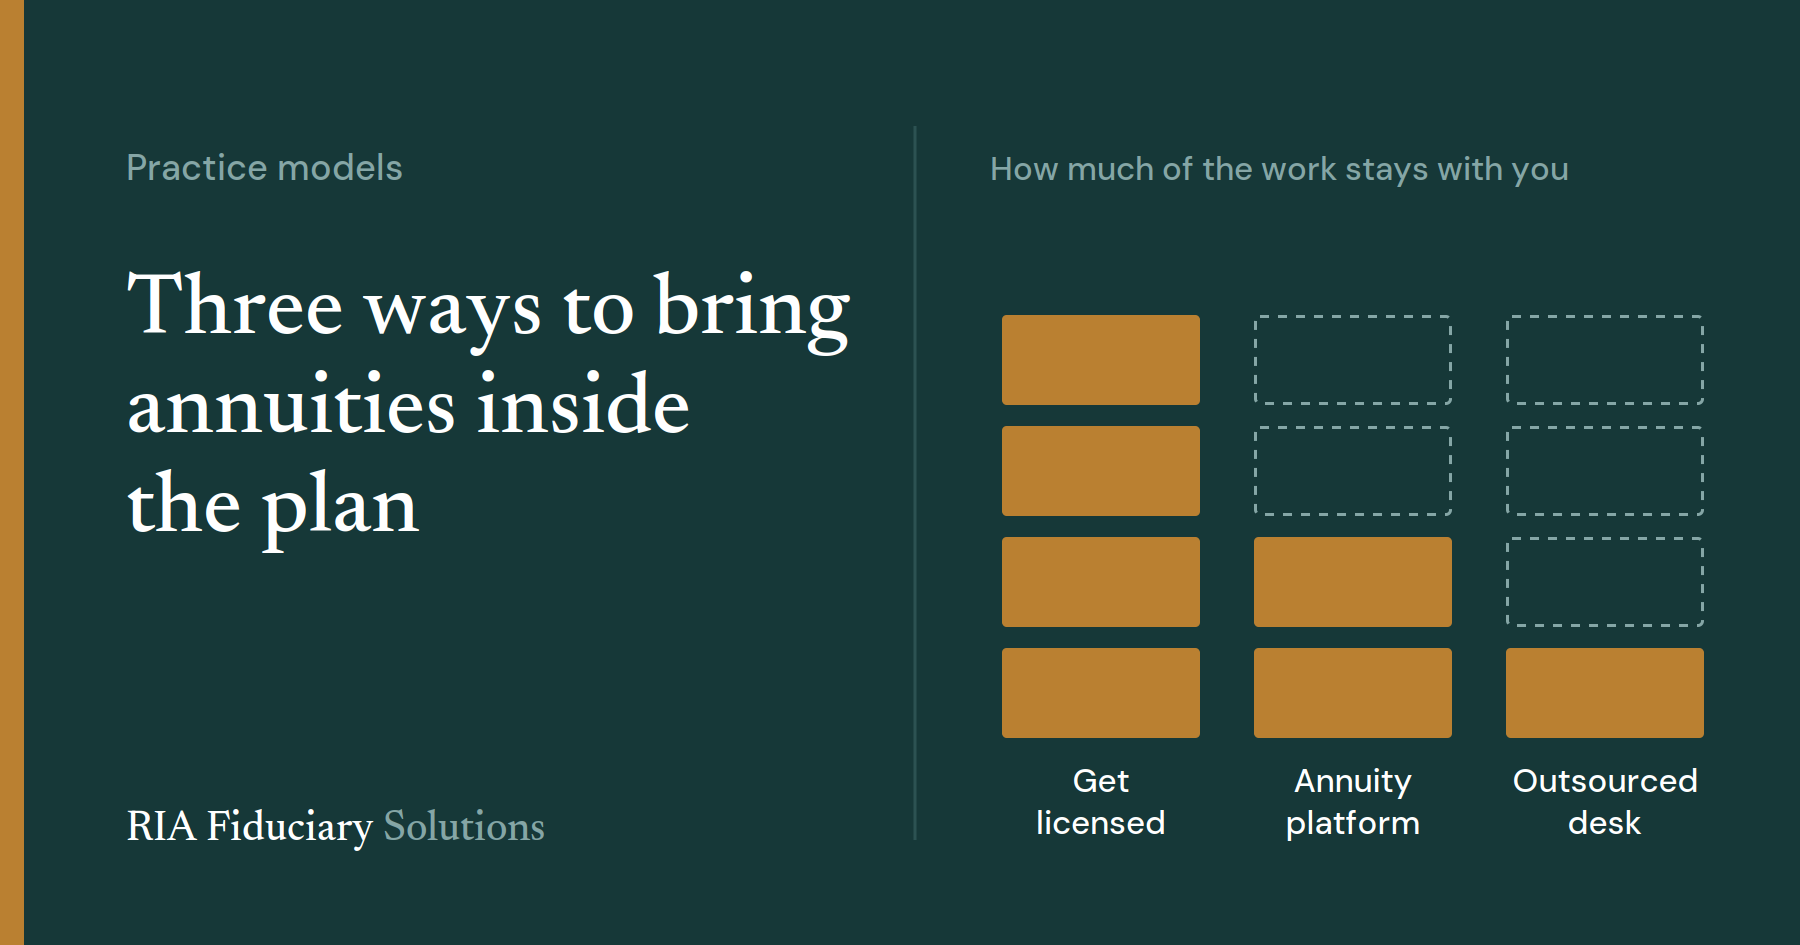
- Getting licensed gives your firm the most control and the heaviest licensing, compliance, and servicing load.
- Annuity platforms give fee-based advisors product access, data, and in some cases billing. Your team still designs the case.
- An outsourced insurance desk (OID) acts as agent of record and can take on design, paperwork, and servicing. How much it takes on varies widely from desk to desk.
Why this decision keeps coming up
Clients nearing retirement ask about guaranteed income, principal protection, and what to do with an old annuity from a previous advisor. If your firm has no clear answer, the client usually finds one, often from a producer who had no part in building the plan.
Over the last several years, the industry has built three main paths for advisors who want to answer those questions inside the plan. Each fits a different kind of firm. The wrong choice costs you either time your team doesn’t have or control you didn’t mean to give up.
Option 1: Get your team insurance licensed
Your advisors obtain state life and annuity licenses, complete carrier product training, get appointed with each carrier they use, and carry errors and omissions coverage. Your firm supervises insurance recommendations under the best-interest annuity suitability standard that most states have adopted.
Works best for firms with steady annuity volume and people who want to own the whole process.
Trade-offs: licensing and continuing education for every advisor involved, appointment paperwork for every carrier, commission compensation that can sit awkwardly with a fee-only model, and the full weight of case design, application, and servicing on your staff.
Option 2: Use an annuity platform or marketplace
Technology platforms give fee-based advisors access to advisory-class annuities, data feeds into portfolio software, and in some cases fee billing on annuity assets. Some are built around a curated shelf of products. Others work as exchanges connecting many carriers to many advisors.
Works best for advisors who are comfortable designing annuity cases themselves and want efficient access and clean integration.
Trade-offs: the platform provides access, while product selection, case design, and the client conversation usually stay with you. Depending on your state, earning a fee on annuity advice can raise its own licensing questions. We cover those in a separate guide.
Option 3: Work with an outsourced insurance desk
A licensed desk serves as agent of record, and your advisor stays planner of record. Depending on the desk, it may handle case design, carrier selection, suitability, electronic applications, policy issue, and ongoing servicing.
Works best for firms without licensed staff, firms with occasional or moderate annuity volume, and firms sitting on complex legacy contracts that need a specialist’s eye.
Trade-offs: you rely on another firm’s people and process, quality varies widely between desks, and you need clear written answers on who owns the client relationship and how the desk is paid.
The three models side by side
| Get licensed | Annuity platform | Outsourced desk | |
|---|---|---|---|
| Agent of record | Your advisor | Varies by platform | The desk |
| Who designs the case | Your team | Usually your team | The desk, with you |
| Licensing load on your firm | High | Low to moderate, depending on state rules | Low |
| Product access | Carriers you’re appointed with | The platform’s shelf | The desk’s carrier relationships |
| Servicing after issue | Your team | Shared with the platform | The desk |
| Best fit | High volume, in-house expertise | Hands-on advisors who want access | Firms that want the work done alongside them |
Seven questions to ask any outsourced desk
- Who is agent of record, and will the desk ever contact my client without me? The answer should be in writing.
- How is the desk paid on each product type? Commission, flat fee, carrier administration fee, or a mix. Ask for it in writing.
- Who actually designs the case? A senior case designer and a service representative are not the same thing.
- How many carriers do you work with, and how is that shelf chosen?
- Will you review contracts my clients already own, and tell me when the right answer is to keep one? A desk that always recommends replacement is telling you something.
- How does contract data get back to my portfolio and CRM systems?
- What happens to servicing if we part ways?
Where RIA Fiduciary Solutions fits
RIA Fiduciary Solutions is an outside insurance and annuity desk built for RIAs and hybrid advisors. You stay planner of record. If your advisors aren’t licensed, cases execute under our license. If they are, we work with your appointments. Our team designs the case with you, handles the paperwork and servicing, and reviews legacy contracts, including telling you when keeping a contract is the better outcome.
We work only with advisors. We don’t market to your clients, and we don’t compete for them.
If you’re weighing what to do with contracts already on your clients’ balance sheets, start with six rider values to check before any 1035 exchange.
Send us a client situation or a legacy contract. We’ll show you how we would approach it, with the trade-offs laid out, before you commit to anything.
Start an analysisQuestions advisors ask
Do I need an insurance license to work with an outsourced insurance desk?
Not for the desk to place the contract as agent of record. Whether your firm can receive a fee tied to annuity assets or annuity advice without an insurance-related license depends on your state. See our state licensing guide and confirm with counsel.
What is the difference between an outsourced insurance desk and an annuity platform?
A platform mainly provides access: products, data, and sometimes billing. An outsourced desk provides licensed people who act as agent of record and, depending on the desk, design and service the case.
Can an outsourced desk review an annuity my client already owns?
Many can. Ask whether the review compares guarantees, fees, and surrender costs, and whether the desk will recommend keeping the contract when that is the better result.